Author: JJ&SW Labs

  • How does the State Pension triple lock work?

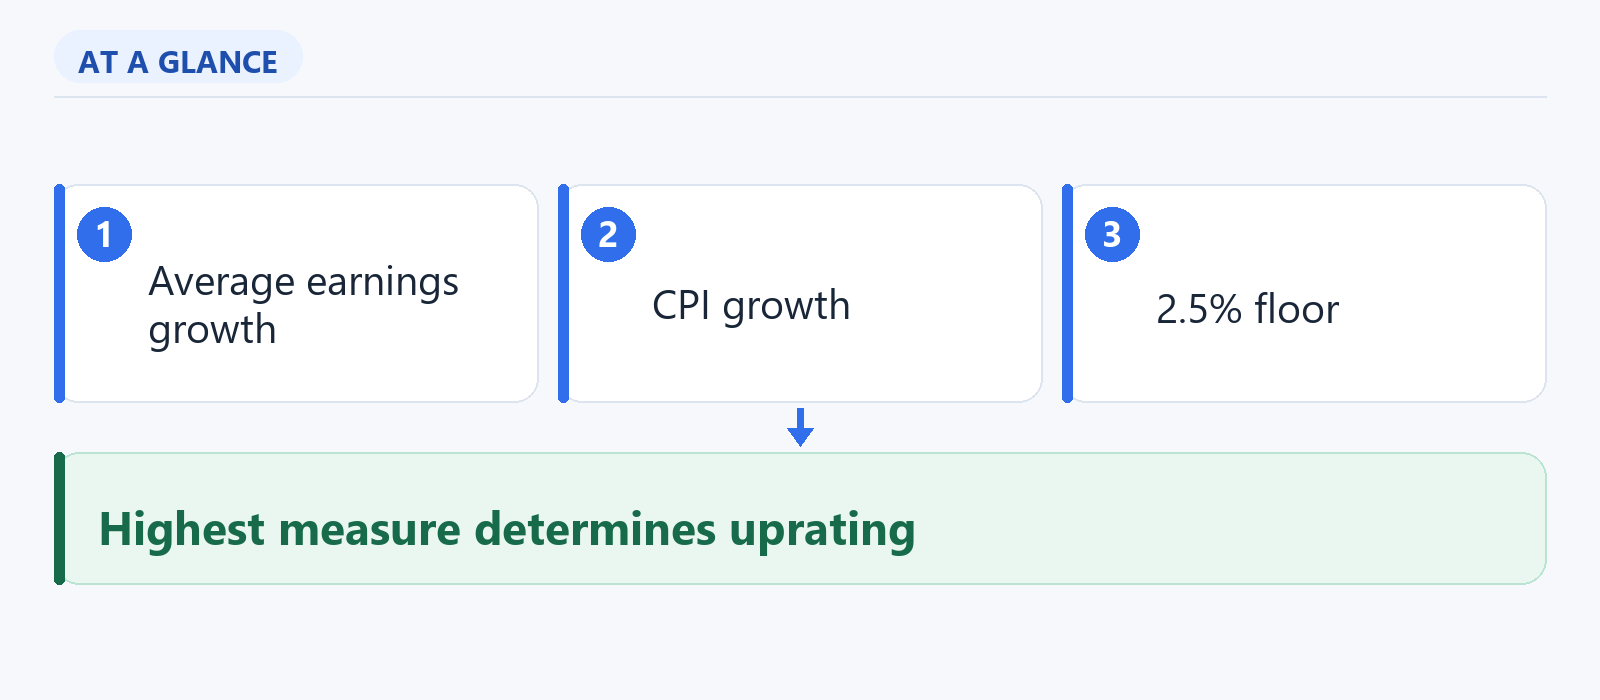
    Diagram showing the State Pension triple lock comparing average earnings growth, CPI growth and a 2.5% floor, with the highest measure determining the uprating rate for covered State Pension amounts.

    The short answer

    The State Pension triple lock is an annual uprating rule. Under the mechanism described in the available government evidence, the basic State Pension and the full-rate new State Pension are increased by whichever is highest in the relevant comparison:

    • average earnings growth;
    • Consumer Prices Index (CPI) growth; or
    • 2.5%.

    In practice, this means the increase is intended to protect the covered State Pension against both rising prices and weak earnings growth, while guaranteeing at least a 2.5% rise under the stated mechanism.

    The exact calculation depends on the applicable policy and reference periods. Those operational details are not established by the evidence available here, so the rule should not be used to calculate an individual’s precise payment increase without checking the current official guidance.

    How the calculation works

    The process can be understood as a three-way comparison:

    1. Measure the relevant growth in average earnings.
    2. Measure the relevant growth in CPI.
    3. Compare both figures with 2.5%.
    4. Use the highest of the three as the uprating rate for the covered pension.

    For example, if earnings growth and inflation were both below 2.5%, the 2.5% floor would be the highest measure. If inflation were higher than both earnings growth and 2.5%, the inflation figure would determine the increase. The same logic applies when earnings growth is the highest measure.

    Those examples explain the mechanism rather than specifying the official measurement periods. The available evidence does not establish every reference date or payment-timing detail.

    Why people describe it as a “ratchet”

    The triple lock can produce a ratchet effect. If one year’s increase is unusually high because earnings or inflation rises sharply, the higher pension amount becomes the starting point for later increases. A subsequent lower rate does not automatically reverse that earlier increase.

    This means that an increase above the earnings measure is not subsequently unwound simply because the relevant measure later falls. The effect is cumulative: the higher base can affect future cash increases even when later uprating rates are more modest.

    This is a policy-analysis explanation of the mechanism’s possible effect, not a calculation of an individual’s entitlement.

    What the triple lock covers—and what it does not necessarily cover

    The evidence supports these important limits:

    • The rule applies to the basic State Pension and the full-rate new State Pension.
    • Some State Pension components from before the 2016 system that fall outside the Triple Lock are described as being uprated by CPI instead.
    • The rule does not by itself determine whether someone qualifies for a State Pension or how much they personally receive. It describes how covered amounts are uprated.

    Could the rule change?

    Yes. The government evidence available for this article describes a planned adjustment to the Triple Lock from April 2030. Therefore, the familiar “highest of earnings, CPI or 2.5%” description should be understood as the mechanism reported in the available evidence and not assumed to remain unchanged indefinitely.

    The date matters: a future policy adjustment could change how uprating works after April 2030. Anyone checking an entitlement or planning around a future payment should use the official rules that apply to the relevant year.

    Bottom line

    The State Pension triple lock works by selecting the highest of average earnings growth, CPI growth and 2.5% for the annual uprating of the basic State Pension and full-rate new State Pension. Its main practical consequence is that unusually large increases can raise the pension’s future baseline rather than being automatically reversed later.

    However, it is not a universal increase for every State Pension component, and the available evidence records a planned adjustment from April 2030. It also does not provide all the reference-period or payment-date details needed to calculate an individual’s exact increase.
    Sources and further reading

  • UK electric car road tax in 2026: what EV owners may have to pay

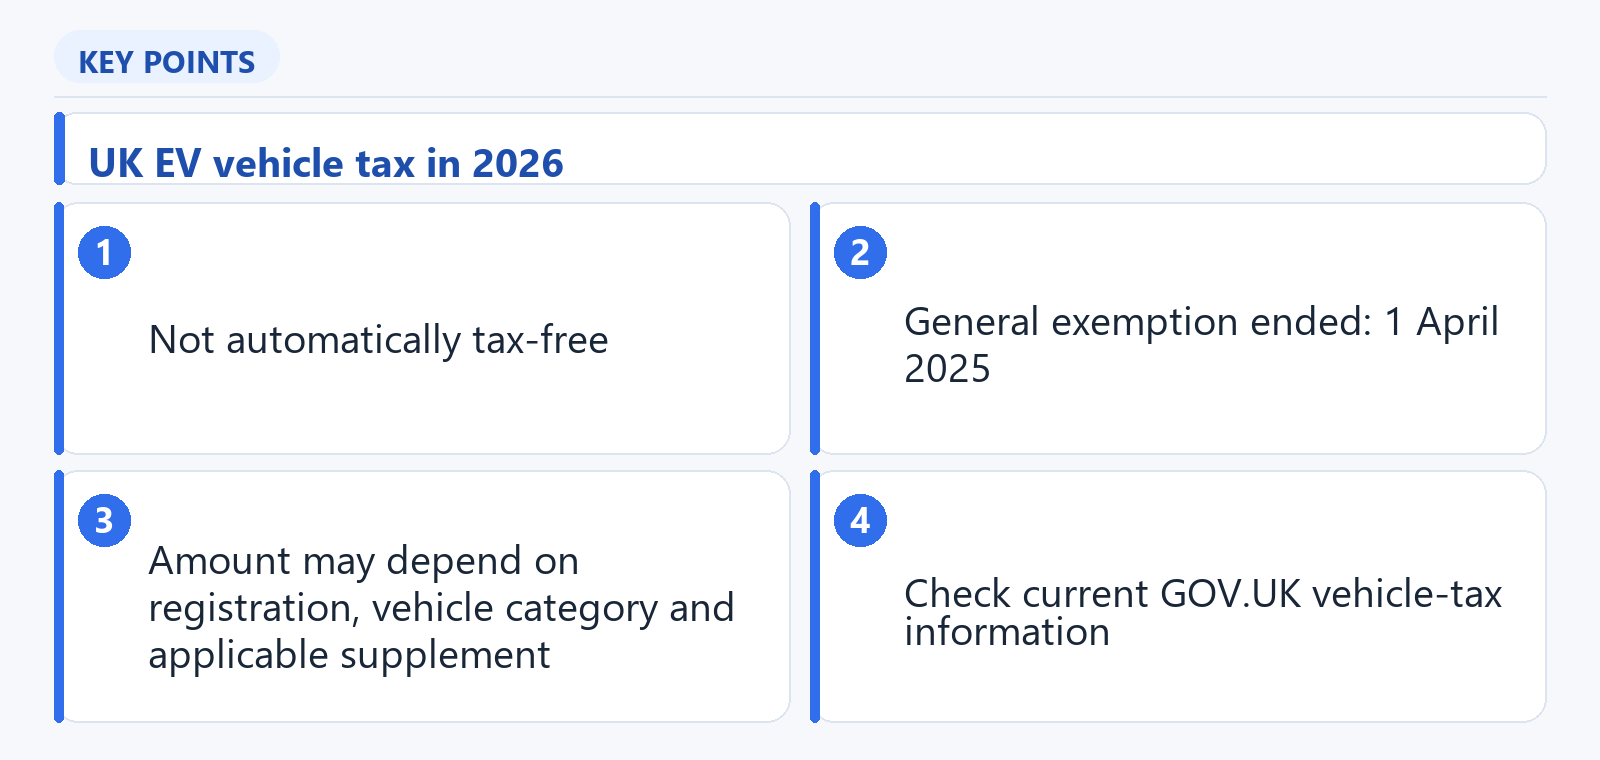
    Editorial infographic summarising that UK electric cars are generally subject to vehicle tax in 2026, with the exact treatment depending on vehicle details and requiring confirmation through current GOV.UK vehicle-tax information.

    Short answer: electric cars are not generally road-tax-free in the UK in 2026. The general exemption ended on 1 April 2025, so an electric car normally needs to be taxed. However, there is no single universal 2026 amount for every EV: the applicable vehicle tax can depend on the vehicle’s category, registration circumstances and whether a supplement applies.

    The tax-status change is supported by current GOV.UK guidance. The available evidence does not include a complete, authoritative 2026 rate table, so treat published figures as indicative until you confirm the vehicle-specific amount through the current GOV.UK vehicle-tax information.

    What changed for electric cars?

    Electric cars ceased to be generally exempt from vehicle tax from 1 April 2025. That means the relevant question in 2026 is usually not whether an electric car must be taxed, but which vehicle-tax treatment and amount apply to that particular car.

    This should not be confused with the vehicle being formally taxed or registered for tax purposes. An electric car should not be assumed to have a zero charge simply because it has an electric powertrain.

    GOV.UK guidance also identifies a continuing exemption for heavy goods vehicles over 3,500kg. That is a specific vehicle-category exception and should not be extended to ordinary electric cars. Hybrid vehicles should likewise not be assumed to receive exactly the same treatment as fully electric cars.

    How much is electric-car road tax in 2026?

    There is no safely supportable single figure for all UK electric cars. Secondary 2026 summaries give examples such as:

    Vehicle or tax situation described in secondary guidance Indicative figure reported Important qualification
    A first-year category £10 Secondary-source guidance; confirm the vehicle’s applicable official category
    A standard category £200 Not a universal EV rate and not a substitute for the current official rate information
    Some cars registered before April 2017 £20 Depends on the relevant registration and tax category
    A standard amount plus an expensive-car supplement Up to about £640 in one summary The supplement, threshold and effective-date details are not consistently established in the available evidence

    These figures are included to explain the range of amounts discussed in current secondary guides, not as a complete 2026 legal rate table. The available guides are not fully consistent, and the evidence does not resolve every threshold or effective-date detail for the expensive-car supplement.

    Before budgeting for a purchase or taxing a vehicle, check the current GOV.UK vehicle-tax information using the car’s registration details. That is the appropriate way to establish the amount and status for an individual vehicle.

    What determines the amount?

    The relevant treatment may depend on several vehicle-specific factors:

    • Registration date: older and newer vehicles can fall into different tax categories. A car registered before April 2017 may not be treated in the same way as a later-registered vehicle.
    • Vehicle category: the rules for an ordinary passenger car should not be assumed to apply to heavy goods vehicles or other categories.
    • First-year treatment: secondary guidance describes a separate first-year amount for some vehicles, but the exact applicable amount should be checked against current official information.
    • Expensive-car supplement: some higher-list-price vehicles may attract an additional charge. The available secondary sources conflict over the relevant threshold and timing, so those details should not be treated as settled without official confirmation.
    • Current tax status: the fact that a vehicle is electric does not, by itself, establish that it is exempt or that its charge is zero.

    The car’s fuel type is therefore only one part of the answer. Registration history and the vehicle’s official category can materially change the result.

    How to check and arrange tax for an electric car

    For a vehicle-specific answer:

    1. Use the current vehicle-tax information and taxing process on GOV.UK.
    2. Check the vehicle using its registration details rather than relying on a general EV rate.
    3. Confirm the displayed tax status, amount and effective treatment before relying on the result for a purchase or payment decision.
    4. If the official record conflicts with a published guide, use the current official record and guidance as the reference point.

    A general article cannot determine the exact liability for a particular car without its vehicle details and the current official information.

    Bottom line

    In the UK, electric cars are generally subject to vehicle tax in 2026 because the general EV exemption ended on 1 April 2025. The amount is not one flat EV rate: it may vary with registration date, vehicle category and any applicable supplement.

    Secondary guides report figures including £10 for a first-year category, £200 for a standard category and £20 for some pre-April-2017 cars, but these are not a complete primary 2026 rate table. The expensive-car supplement is particularly unsuitable for an unqualified answer because the available sources disagree about its threshold and timing.

    For the final amount or tax status of a specific electric car, check the current GOV.UK vehicle-tax information.

    Sources and further reading

  • What Is Mignonette Sauce? Ingredients, Traditional Uses, and Variations

    Mignonette sauce is a condiment made primarily from minced shallots, vinegar, and pepper. It is commonly served alongside raw oysters, clams, and other seafood.

    It is an uncooked sauce or relish with a vinegar-based flavor profile, and recipes can vary in their ingredients and proportions.

    The Classic Formula

    A common traditional-style mignonette relies on three core components:

    • Shallots: Finely minced shallots.
    • Vinegar: Red wine vinegar is used in many classic formulations.
    • Pepper: Pepper is included in the conventional combination.

    The ingredients are mixed before serving.

    How It Is Served

    Mignonette is served alongside raw oysters, clams, and other seafood. Diners can spoon it directly onto the shellfish before eating.

    Variations and Recipe Exceptions

    Although vinegar, shallots, and pepper form a common traditional-style base, culinary preparations vary:

    • Vinegar Alternatives: Other types of vinegar may be substituted depending on the desired flavor. Some variations also incorporate citrus.
    • Seasoning Adjustments: Pepper, salt, and sugar may be included or omitted depending on the recipe. Some preparations use additional seasoning to adjust the flavor.
    • Modern Profiles: Contemporary variations may include spicy ingredients, fruit, herbs, or sweet elements.

    The vinegar, shallot, and pepper combination is therefore a conventional base rather than an exclusive formula; mignonette recipes can differ while remaining variations on the same seafood accompaniment.

    Sources and further reading