Tag: State Pension

  • What Does the Triple Lock Mean for UK Pensioners?

    What Does the Triple Lock Mean for UK Pensioners?

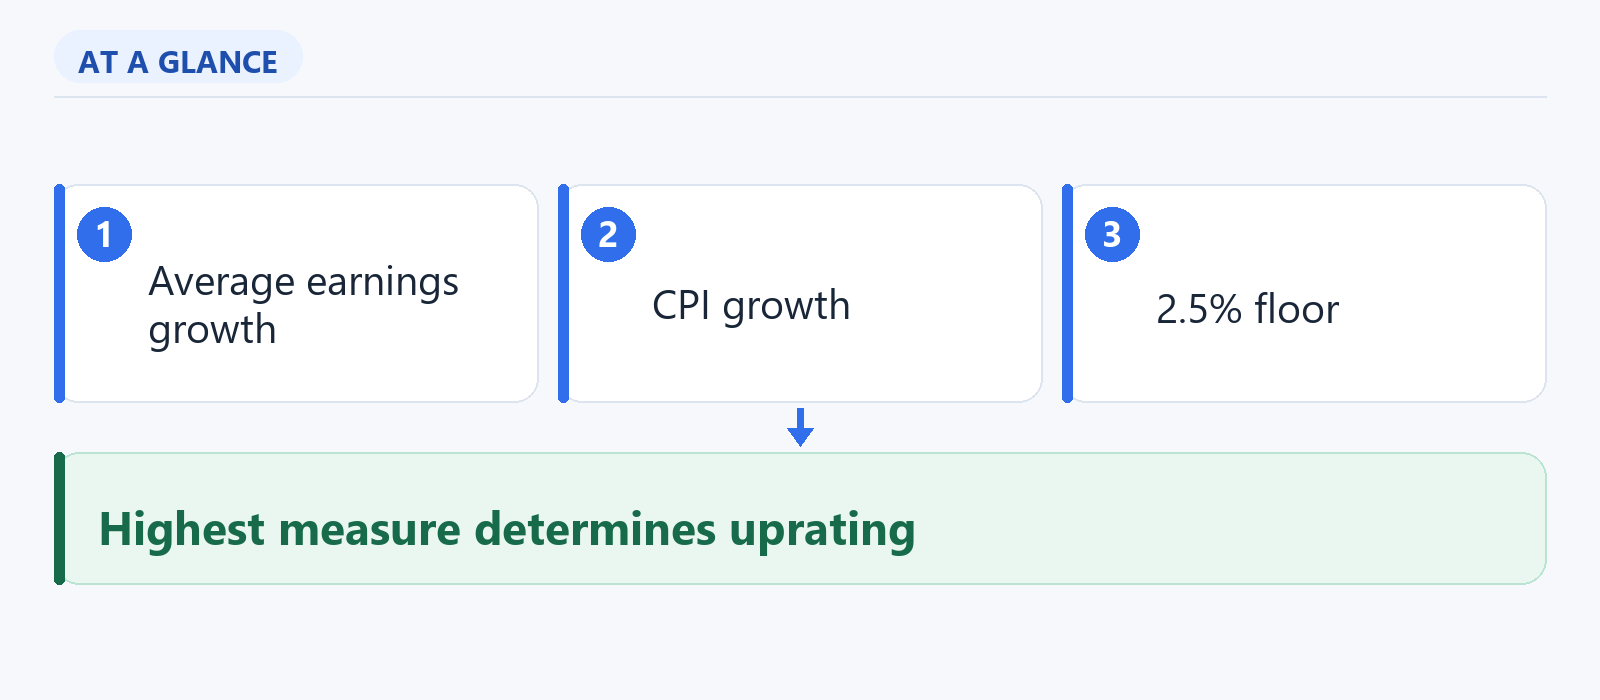
    The pension triple lock is a UK annual State Pension uprating rule. It uses the highest of three measures—average earnings growth, inflation, or 2.5%—to determine the increase applied to the relevant State Pension.

    It is an uprating mechanism rather than a separate benefit payment.

    How the Triple Lock Formula Works

    Each year, the government assesses three distinct benchmarks to determine the increase applied to the State Pension:

    1. Average earnings growth: A measure of the percentage increase in average earnings across the UK economy.
    2. Inflation: The rate of price inflation, measured using the Consumer Price Index (CPI).
    3. A 2.5% component: The third measure in the triple lock comparison.

    Whichever of these three percentages is greatest determines the uprating rate for the relevant State Pension under the triple lock rule.

    Which Pensions Are Covered?

    The triple lock does not apply universally across all retirement benefits. According to official Department for Work and Pensions (DWP) analysis, the policy specifically covers:

    • The basic State Pension: Payable to individuals who reached State Pension age before 6 April 2016.
    • The new State Pension: Specifically the full-rate new State Pension introduced for individuals reaching State Pension age on or after 6 April 2016.

    The official analysis distinguishes these covered State Pension components from other components that are not covered by the triple lock.

    Reference Periods, Policy Continuity, and Caveats

    While the highest-of-three rule defines the core policy, applying it in practice depends on specific reporting periods and parliamentary decisions:

    • Reported reference periods: Secondary sources have reported May-to-July earnings growth and September CPI as reference points in historical or general explanations of the uprating process. These reported reference points should not be treated as confirmation of a particular year’s calculation.
    • Policy adjustments and historical exceptions: A secondary source reports that the earnings link was temporarily adjusted or suspended for 2022/23. This was a past exception.
    • Future policy changes: The official analysis reports a government commitment to retain the triple lock through the current Parliament and identifies a planned policy adjustment from April 2030. These are qualified future-policy statements; they do not establish a definitive current-year uprating, and future uprating rules may change.

    In summary, the triple lock is an annual UK State Pension uprating mechanism. For the basic State Pension and full-rate new State Pension within the stated scope, it uses whichever is highest among average earnings growth, CPI inflation, and 2.5%. The available evidence also includes qualified statements about policy continuity and a planned adjustment from April 2030, so the rule should not be treated as an unconditional or permanent guarantee in its current form.
    Sources and further reading

  • How does the State Pension triple lock work?

    Diagram showing the State Pension triple lock comparing average earnings growth, CPI growth and a 2.5% floor, with the highest measure determining the uprating rate for covered State Pension amounts.

    The short answer

    The State Pension triple lock is an annual uprating rule. Under the mechanism described in the available government evidence, the basic State Pension and the full-rate new State Pension are increased by whichever is highest in the relevant comparison:

    • average earnings growth;
    • Consumer Prices Index (CPI) growth; or
    • 2.5%.

    In practice, this means the increase is intended to protect the covered State Pension against both rising prices and weak earnings growth, while guaranteeing at least a 2.5% rise under the stated mechanism.

    The exact calculation depends on the applicable policy and reference periods. Those operational details are not established by the evidence available here, so the rule should not be used to calculate an individual’s precise payment increase without checking the current official guidance.

    How the calculation works

    The process can be understood as a three-way comparison:

    1. Measure the relevant growth in average earnings.
    2. Measure the relevant growth in CPI.
    3. Compare both figures with 2.5%.
    4. Use the highest of the three as the uprating rate for the covered pension.

    For example, if earnings growth and inflation were both below 2.5%, the 2.5% floor would be the highest measure. If inflation were higher than both earnings growth and 2.5%, the inflation figure would determine the increase. The same logic applies when earnings growth is the highest measure.

    Those examples explain the mechanism rather than specifying the official measurement periods. The available evidence does not establish every reference date or payment-timing detail.

    Why people describe it as a “ratchet”

    The triple lock can produce a ratchet effect. If one year’s increase is unusually high because earnings or inflation rises sharply, the higher pension amount becomes the starting point for later increases. A subsequent lower rate does not automatically reverse that earlier increase.

    This means that an increase above the earnings measure is not subsequently unwound simply because the relevant measure later falls. The effect is cumulative: the higher base can affect future cash increases even when later uprating rates are more modest.

    This is a policy-analysis explanation of the mechanism’s possible effect, not a calculation of an individual’s entitlement.

    What the triple lock covers—and what it does not necessarily cover

    The evidence supports these important limits:

    • The rule applies to the basic State Pension and the full-rate new State Pension.
    • Some State Pension components from before the 2016 system that fall outside the Triple Lock are described as being uprated by CPI instead.
    • The rule does not by itself determine whether someone qualifies for a State Pension or how much they personally receive. It describes how covered amounts are uprated.

    Could the rule change?

    Yes. The government evidence available for this article describes a planned adjustment to the Triple Lock from April 2030. Therefore, the familiar “highest of earnings, CPI or 2.5%” description should be understood as the mechanism reported in the available evidence and not assumed to remain unchanged indefinitely.

    The date matters: a future policy adjustment could change how uprating works after April 2030. Anyone checking an entitlement or planning around a future payment should use the official rules that apply to the relevant year.

    Bottom line

    The State Pension triple lock works by selecting the highest of average earnings growth, CPI growth and 2.5% for the annual uprating of the basic State Pension and full-rate new State Pension. Its main practical consequence is that unusually large increases can raise the pension’s future baseline rather than being automatically reversed later.

    However, it is not a universal increase for every State Pension component, and the available evidence records a planned adjustment from April 2030. It also does not provide all the reference-period or payment-date details needed to calculate an individual’s exact increase.

    Sources and further reading

  • UK State Pension Age by Date of Birth: How to Check Yours

    The short answer

    Your UK State Pension age is determined mainly by your date of birth under the legislated State Pension age timetable. The safest way to find your exact result is to use the official GOV.UK State Pension age checker, which provides the current date-of-birth-based calculation.

    The official timetable establishes a transition from State Pension age 66 to 67, followed by a planned increase from 67 to 68. However, the evidence available for this article does not include the timetable’s detailed date-of-birth tables, so an exact birthday-to-age mapping should be checked directly in the current GOV.UK service rather than inferred from a summary table.

    How to check your State Pension age

    1. Open the GOV.UK service titled “Check your State Pension age.”
    2. Enter your date of birth when prompted.
    3. Use the result as the current indication of the earliest age at which you can receive the State Pension.

    This check is preferable to relying on an old chart or a third-party summary because the timetable is subject to review and the applicable result can depend on the current legislation and government guidance.

    What the timetable means

    The State Pension age timetable provides for:

    • State Pension age being equalised between women and men;
    • a phased transition from age 66 to age 67; and
    • a planned increase from age 67 to age 68.

    The future timetable is not permanently fixed. State Pension age is reviewed regularly, including through five-year reviews. In particular, the planned 67-to-68 timetable may change following a future review and requires Parliamentary approval. Treat any historical table as potentially out of date and verify the result using the current GOV.UK checker.

    Important distinctions

    State Pension age is not the same as your workplace or personal pension age. A private pension, workplace scheme or other retirement arrangement can have its own access rules. Checking your State Pension age does not determine when you can access those other pensions.

    State Pension age is the earliest age for receiving the State Pension. It does not necessarily mean you must stop working. GOV.UK guidance indicates that you can continue working after reaching State Pension age.

    Bottom line

    Use your date of birth with the current GOV.UK State Pension age checker to obtain the applicable result. The broad statutory timetable moves from 66 to 67 and plans a later move from 67 to 68, but the detailed mapping and future position must be verified because the timetable is reviewed and can change.

    Sources and further reading